BNG Pricing Report: November 2026
Our November 2026 report explores what units are selling in the market, where demand is coming from, how much buyers are paying by pairing Natural England’s allocation records with prices from 414 habitat banks, up from 186 a year ago. We give developers, consultants, and landowners a broader evidence-based guide to their BNG decisions.
BNG Unit Prices in England – November 2026
| Habitat Type | Habitat Distinctiveness | In LPA / NCA Price | Supply Level |
|---|---|---|---|
| Other Neutral Grassland | Medium | £23,500 | Abundant |
| Woodland and Forest | Medium | £34,536 | Abundant |
| Heathland and Shrub | Medium | £29,256 | Abundant |
| Lakes/Ponds Non Priority Habitat | Medium | £40,500 | Medium |
| Lowland Meadows | Very High | £30,000 | Abundant |
| Watercourses - Ditches | Medium | £90,000 | Medium |
| Watercourses - Other Rivers and Streams | High | £132,000 | Uncommon |
| Watercourses - River (Priority Habitat) | Very High | £153,000† | Rare |
| Individual Trees | Medium | £32,150 | Medium |
| Traditional Orchards | High | £29,200 | Medium |
| Wet Woodland | High | £43,995 | Uncommon |
| Mixed Deciduous Woodland | High | £35,650 | Medium |
| Open Mosaic Habitat | High | £40,000 | Uncommon |
| Floodplain Wetland Mosaic | High | £34,549 | Medium |
| Hedgerows | Medium | £26,793 | Uncommon |
| Hedgerows | High | £26,532 | Medium |
| Wood Pasture and Parkland | Very High | £35,000 | Uncommon |
| Calcareous Grassland | High | £38,250† | Rare |
Source: Biodiversity Units UK, November 2026 BNG Pricing Report. Prices shown represent one off-site BNG unit, assuming no Spatial Risk Multiplier applies.
† Limited data: use with caution; England price used where local data is thin.
| Habitat Type | Habitat Distinctiveness | In LPA / NCA Price | Supply Level |
|---|---|---|---|
| Other Neutral Grassland | Medium | £23,500 | Abundant |
| Woodland and Forest | Medium | £33,368 | Abundant |
| Heathland and Shrub | Medium | £26,083 | Abundant |
| Lakes/Ponds Non Priority Habitat | Medium | £51,225 | Medium |
| Lowland Meadows | Very High | £30,000 | Abundant |
| Watercourses - Ditches | Medium | £87,000 | Medium |
| Watercourses - Other Rivers and Streams | High | £129,150 | Medium |
| Watercourses - River (Priority Habitat) | Very High | £150,000 | Rare |
| Individual Trees | Medium | £29,694 | Medium |
| Traditional Orchards | High | £30,600 | Medium |
| Wet Woodland | High | £38,750 | Rare |
| Mixed Deciduous Woodland | High | £42,200 | Medium |
| Open Mosaic Habitat | High | £36,500† | Rare |
| Floodplain Wetland Mosaic | High | £32,000 | Medium |
| Hedgerows | Medium | £25,788 | Uncommon |
| Hedgerows | High | £26,043 | Medium |
| Wood Pasture and Parkland | Very High | £38,500† | Scarce |
| Calcareous Grassland | High | £38,250 | Medium |
Source: Biodiversity Units UK, November 2026 BNG Pricing Report. Prices shown represent one off-site BNG unit, assuming no Spatial Risk Multiplier applies.
† Limited data: use with caution; England price used where local data is thin.
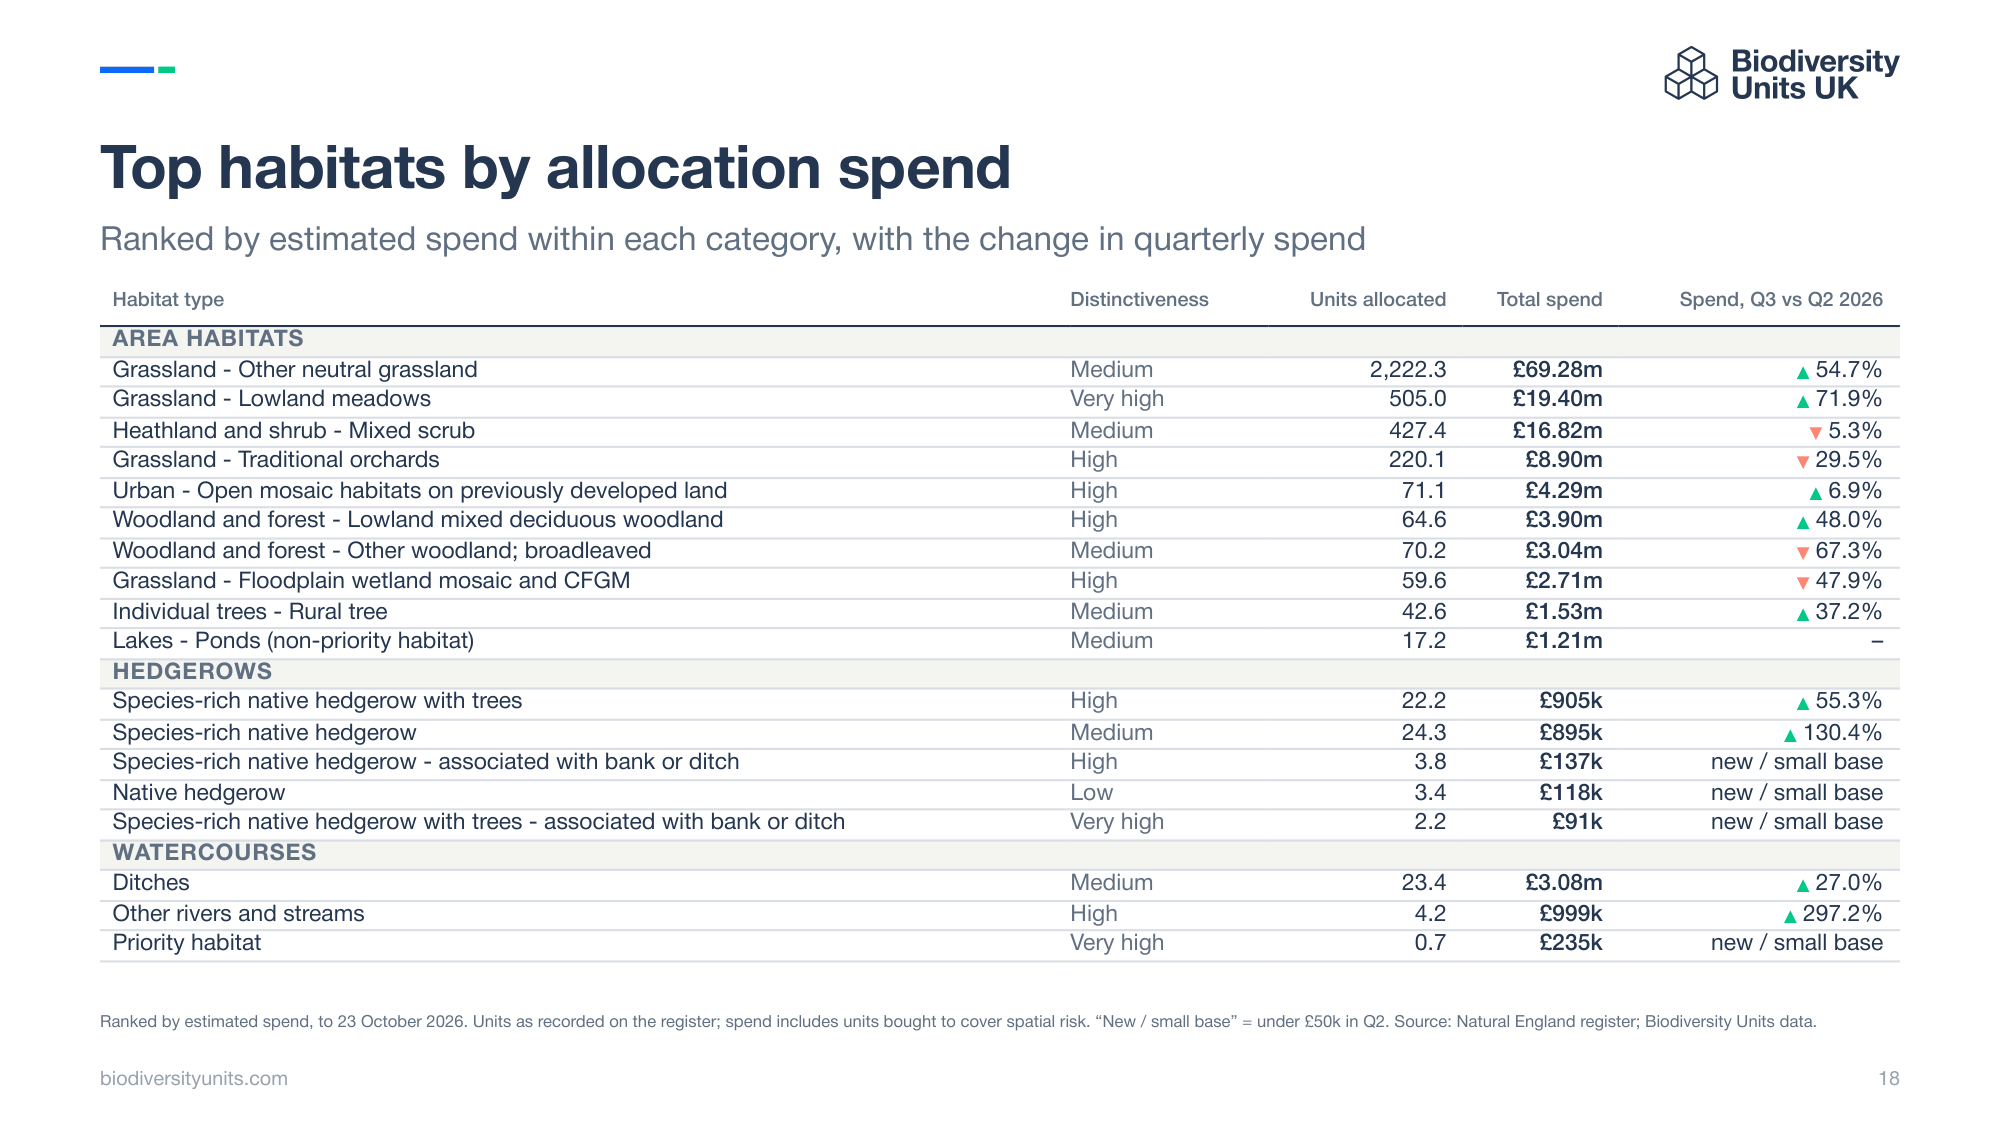
£143 million in estimated BNG spending
Our November 2026 report puts cumulative estimated spending on BNG units at £143 million, up from £93 million in our July report.
Activity is picking up too. In Q3 2026, recorded allocations reached 865, an increase of 39% on the previous quarter, with their estimated value rising 35% to £32.8 million.
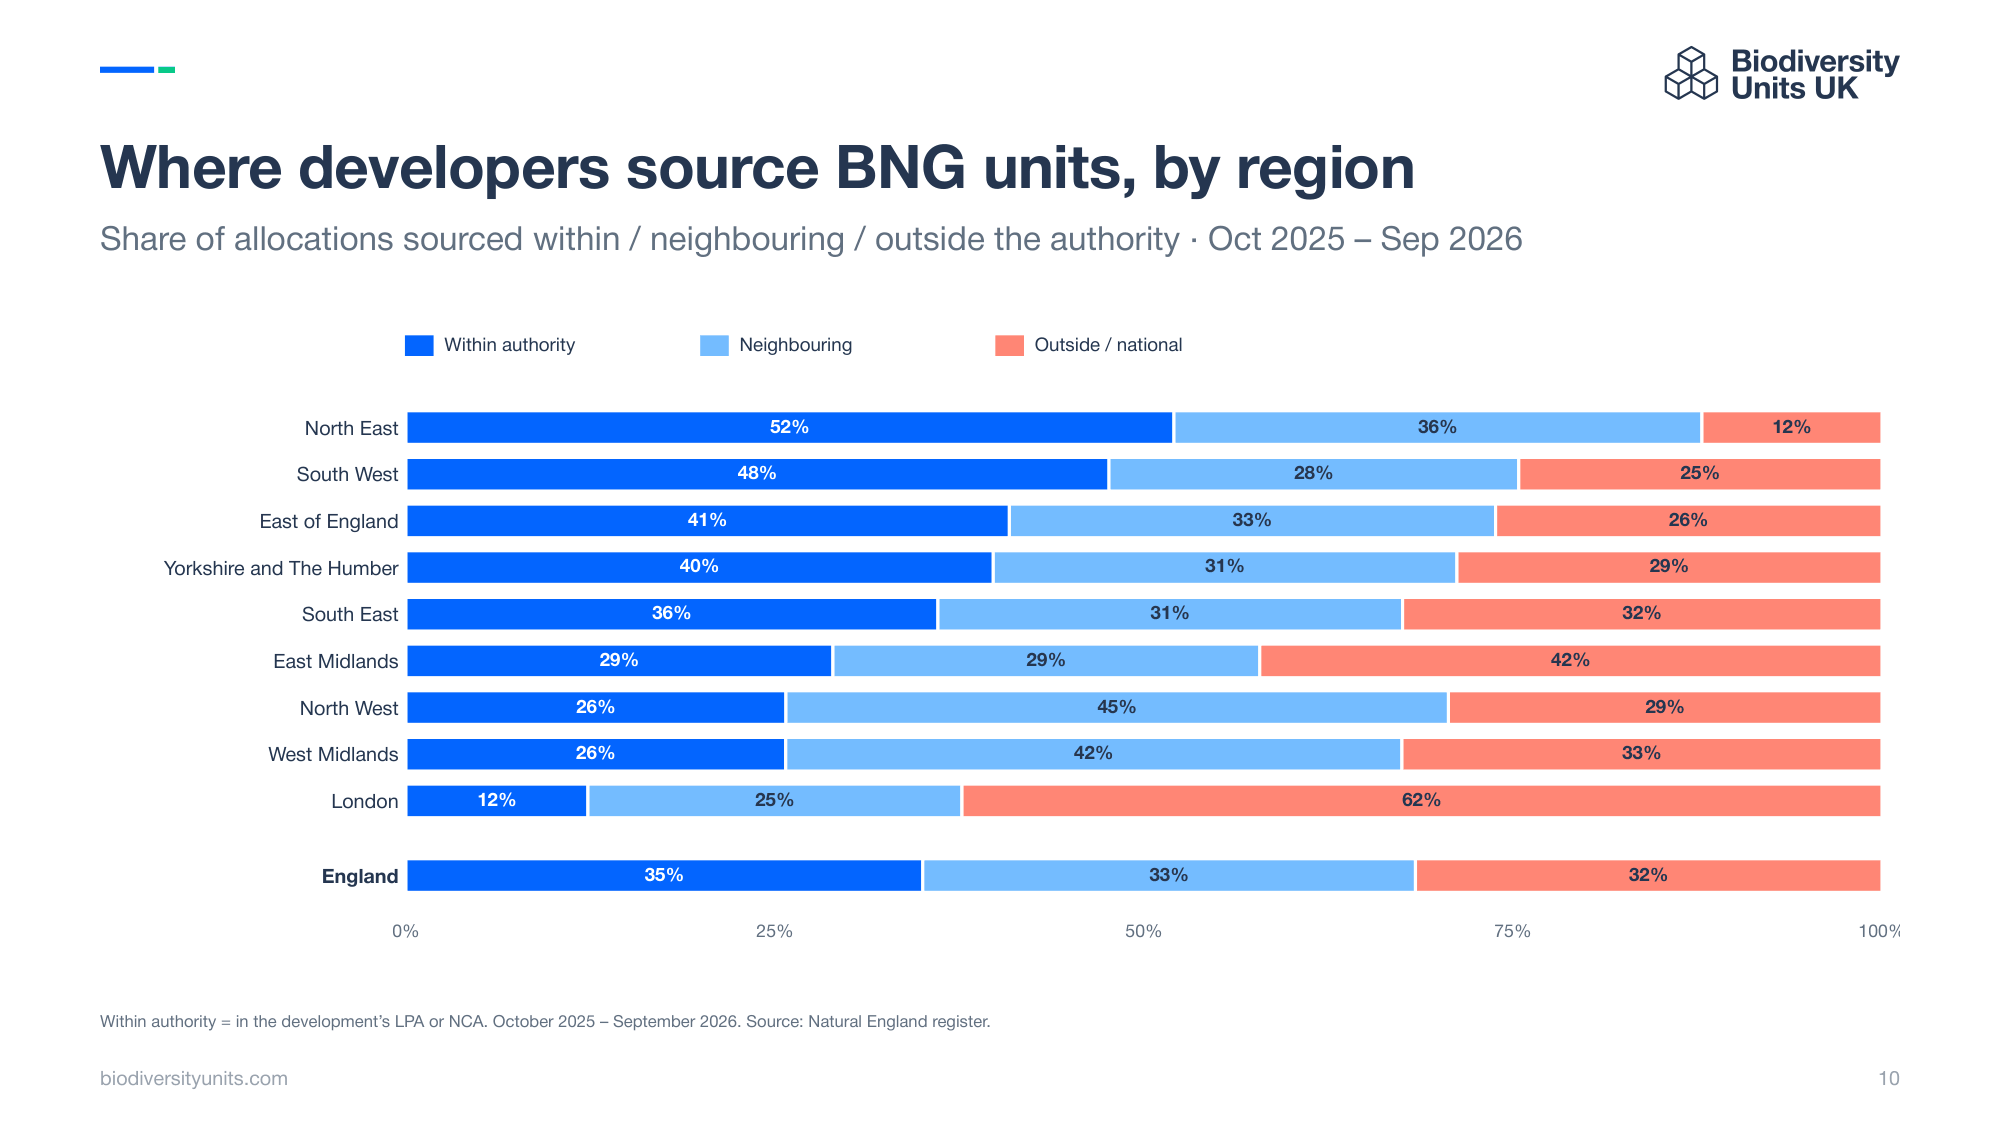
Supply has more than doubled over the past year. England now has 414 registered habitat banks, compared with 186 twelve months ago. But more supply nationally doesn't always mean more choice locally.
What's new in this report:
Our most comprehensive pricing picture yet
Nearly 10,000 pricing data points underpin the latest North and South benchmarks, with breakdowns for all nine English regions. Combined with Natural England's allocation records, they show how prices, purchasing activity and supply are changing.A broader supplier market
We've identified 169 habitat bank operators, including 131 running a single bank. Even the largest identified operator accounts for just 11% of registered banks, making visibility across the wider market increasingly valuable.Grassland continues to lead spending
Other Neutral Grassland remains the most purchased area habitat by estimated spend, at £69.28 million. Lowland Meadows follows at £19.40 million.
What this means if you're buying BNG units
There are more suppliers to consider, more pricing data to work with, and falling prices across many habitat types.
Finding the right units still takes more than comparing headline prices. Local availability remains uneven, and registration alone doesn't confirm that a habitat bank has suitable units available to buy. Understanding where units can be used, what is available and how spatial risk affects the total cost remains essential to securing the right match for your project.
Stay up to date.
Sign up to our mailing list in order to stay up to date with news and developments on how Bio Net Gain is affecting English Commercial Property Development.